Find out what you can borrow.
Tell me what you're planning. I compare 50+ lenders across the GTA and surrounding areas and reply personally within one business day. No obligation.
- Pre-approvals, renewals and refinancing
- Self-employed and newcomer programs
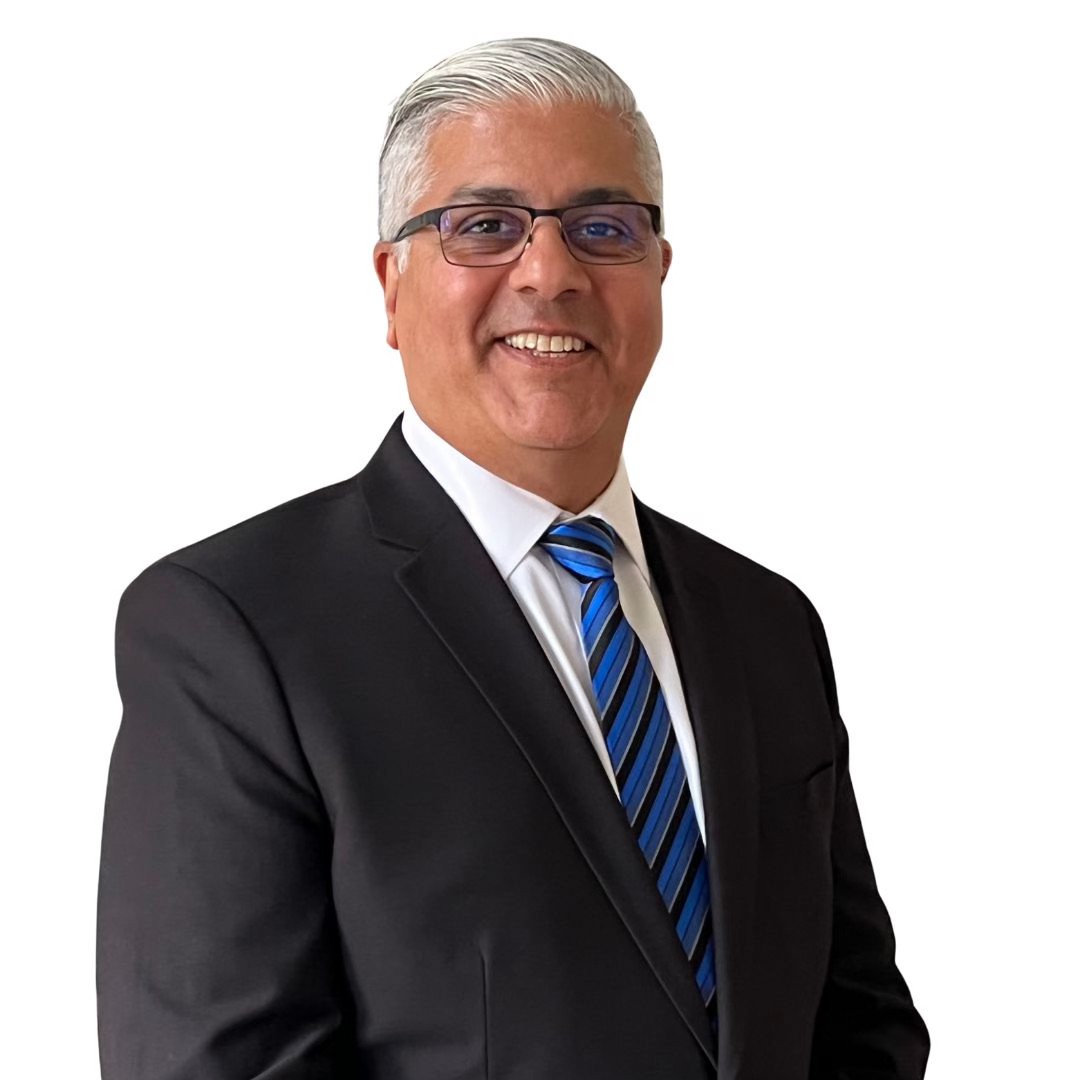
Meet Aly
I've bought three homes of my own as our life changed, so I know how the "move now or wait?" question feels. That's why I start with you instead of the rates: what are you trying to do, and what does your timing look like? From there I explain things the way I'd want them explained to me, so we make the decision together. And while your file is with a lender, I'm the one who calls to say there's no news yet.
What are you trying to do?
Pick the closest match to your situation.
Pre-Approvals
First-Time Homebuyers
Self-Employed Mortgage Solutions
Mortgage Renewals
Refinancing
Newcomer to Canada Mortgages
Debt Consolidation
Bridge Financing
Investment Properties

Start with the Roadmap.
A short guide to the four stages of getting a mortgage: what happens, what I'll need from you and how long each step usually takes. Written in plain language, not mortgage-speak.
Get the RoadmapQuestions I hear most.
Should I accept my lender's mortgage renewal offer?
Not automatically. Your lender's first renewal offer isn't always the best one available to you. Comparing across 50+ lenders before you sign can lower your payments, shorten your amortization or open up equity.
Can self-employed buyers get a mortgage in Ontario?
Yes. It's just documented differently from a salaried employee's income. Lenders who work with business owners look at your income stability, credit and assets.
Can newcomers to Canada qualify for a mortgage without Canadian credit history?
Yes. Several lenders have newcomer programs that use other proof of financial reliability instead of a Canadian credit history.
What is bridge financing and when do I need it?
Bridge financing is short-term funding that covers the gap when you buy a new home before your current one sells.
How is a mortgage pre-approval different from a pre-qualification?
With a pre-approval, a lender reviews your income, credit and down payment, so you shop with a real number. Lenders can hold a rate for a set period, typically 60 to 130 days depending on the lender, while you shop. A pre-qualification is a rougher estimate that isn't verified.
Ready to talk it through?
Book a 30-minute call. We'll go through your goals together, with no obligation.